Are Philadelphia Luxury Condos a Good Investment? What 40 Years of Market Cycles Reveal.
The honest answer is: some are. Some aren’t.
I’ve been developing residential real estate in Philadelphia for more than 40 years, long enough to watch luxury housing move through repeated booms and downturns. I’ve built through recessions, recoveries, a housing crash, a pandemic, and the fastest interest-rate increase in a generation.
Those cycles have taught me that a luxury condominium is not automatically a good investment simply because it is expensive, new, or located in Center City. The properties that tend to hold value best share durable qualities — and those qualities are usually established long before it’s sold.
A condominium begins protecting its value when the first decisions about the building are made. Where will it sit? Will the views remain protected? Will the architecture still feel distinctive in 10 or 20 years? Is it built to age well? Will the home’s design appeal to the next generation of buyers? Will the amenities be relevant? Is the neighborhood evolving and improving? How difficult would it be to build the same product again?
Key Takeaways
- Not every luxury condominium performs alike. Durable value begins with location, design, construction, views, amenities and sound building finances.
- Every new condominium becomes a resale. For a condominium to hold its value, the building must be appealing to a buyer in five, 10 or 20 years from now.
- The developer matters twice: in what gets built and in the discipline used to protect value when markets turn.
- Scarcity and replacement cost matter. Today's difficult building environment may limit tomorrow's supply and make the existing new product available now even more desirable.
Every new condominium eventually becomes a resale. The real test of a luxury building is not simply whether a developer can sell it when it is new. It is whether someone else will want to buy it from you years later. That is what I mean by protected value — and 40 years of market cycles show why it matters.
Before Luxury Condominiums, There Were Loft Apartments
When I began developing in Philadelphia in the 1980s, the idea of affluent people choosing an urban lifestyle didn’t exist. Conventional wisdom held that successful people gravitated to the suburbs. Philadelphia was losing population quickly, and former factories and warehouses stood dark and empty — remnants of an industrial and manufacturing economy that had moved overseas.
Pessimists had a dismissive outlook. I saw it differently. Those defunct buildings represented opportunity. All I needed to do was strip away decades of neglect and turn them into something new.
There was something electrifying about that. These weren’t suburban houses transplanted into the city. We created a new category of high-end living: loft-style apartments. It felt young, modern, and distinctly urban — twelve-foot ceilings, huge windows, bright white walls, exposed brick and old wood beams, open kitchens and expansive rooms without the formality of the traditional apartment. The imperfections of the old buildings weren’t hidden; they were part of the appeal.
A new generation of residents wanted them. Young professionals were rediscovering forgotten urban neighborhoods. They wanted to walk to restaurants, discover the city around them, and live somewhere that didn’t look like where their parents lived. We weren’t simply converting old buildings. We were testing a much bigger idea: would people with choices call Philadelphia home again?
They did. Those early loft dwellers helped establish something Philadelphia had been missing: a genuine market for upscale urban living.
Back then, the amenity wasn’t a fitness center, a screening room, or a rooftop garden. The amenity was the city itself.
Then the Buyer Grew Up
By the early 2000s, the market was changing. Interest rates had fallen dramatically from the double-digit levels of the 1980s, credit was more available, household wealth was growing, and a national housing boom was underway.
But something demographic was happening too. The generation that came of age as Philadelphia was rediscovering urban living was now older. Many had moved to the suburbs to raise families. They advanced their careers and accumulated wealth. Now their children were adults and leaving home, and the large suburban house was feeling empty and burdensome. The city was calling again.
This time, though, they weren’t looking for a converted loft. They wanted space, views, parking, security, fitness facilities, pools, concierge service, and beautiful finishes. They wanted enough room for their adult children and grandchildren to visit, without the maintenance of a large suburban property. Most of all, they wanted everything they remembered loving about city life: restaurants, theater, music, architecture, walkability, and the energy of being in the middle of things.
We saw that buyer very clearly at Symphony House, where two-thirds of buyers were suburban empty nesters. The city was still the amenity. But now the buyer wanted the building to be one, too.
2007: When the Market Broke
Then came the financial crisis. In August of 2007, the losses in the subprime market froze global credit. By December of 2007, we were in the Great Recession. Buyers retreated. Financing disappeared. Projects stalled. Buildings that had looked promising only a year or two earlier suddenly had large numbers of unsold residences.
Philadelphia was not immune. Sales activity fell sharply, and distressed inventory began to shape buyer psychology. The Murano became one of the most visible examples: in 2009, unsold residences went to auction, with minimum bids advertised at as much as 50 percent below original asking prices. The auction moved units, but it also sent a message far beyond that building — wait long enough, buyers reasoned, and luxury developers might capitulate on price.
The Ritz-Carlton Residences told a related story, on an even longer timeline. The building broke ground in 2006 and was completed in 2009, delivering a large number of new residences directly into the worst of the downturn. Selling that much inventory into a shrunken buyer pool took years longer than it would have in a normal market — the building was still working toward sellout as late as 2021. It eventually got there, but the lesson stuck with me: it isn’t only whether a building is well built and well located. It’s also how much new supply is chasing the same buyers at the same moment.
That matters because a distressed transaction can affect more than the seller. It can reset expectations across an entire market, including for properties that aren’t distressed and don’t share the same economics. When you buy a condominium, you are also buying into decisions other people will make about the building’s value — during the original sellout and for decades afterward.
In 2011, when I was appointed receiver of 10 Rittenhouse Square after its lender, iStar Financial, took control, realtors came in expecting another fire sale like the Murano. Some offers were as much as $1 million below asking price. We chose a contrarian strategy. Working with the lender, we refused to auction the residences or chase the market down. Instead, we redesigned floor plans, upgraded finishes, improved the amenities, and focused on making the product best in class. Then we held the line on price. I called this the protected-value strategy.
It wasn't about pretending the market hadn't changed. It had. It was about distinguishing between a temporarily distressed market and the underlying long-term value of exceptional real estate.
Six months after we took over sales at 10 Rittenhouse, things turned around. It took patience and resilience, but it was worth it — particularly for buyers. 10 Rittenhouse took off, becoming the first high-rise condominium property to cross the $1,000-per-square-foot threshold. That success led the same lender to bring us in on another distressed high-end condominium property, Two Liberty Place in February of 2015. Again, we reworked the product and repositioned the residences, achieving another sellout.
The Great Recession showed me something I have carried through every cycle since: price and value can become temporarily disconnected. A distressed sale may establish a transaction price. It does not necessarily establish the long-term value of comparable real estate.
2015–2018: The Market Comes of Age
What happened next may be the most consequential chapter in Philadelphia’s luxury residential history. The economy fully recovered. Interest rates remained historically low. Household balance sheets improved. But recovery alone does not explain what happened in Center City. The buyer had changed, and Philadelphia had changed with them.
Center City had become a far richer place to live than it had been a generation earlier. The restaurant scene had exploded. Cultural institutions were thriving. Parks and public spaces were improving. Universities and medical institutions were expanding. Neighborhoods were becoming more walkable, active, and connected. And affluent baby boomers were reaching the exact life stage when many began rethinking where and how they wanted to live.
In 2014, more than 100 Center City condominiums sold for $1 million or more. Yet developers and lenders were still cautious — the pain of the Great Recession was still fresh, and financing large for-sale buildings remained difficult. That year, I made a decision that reflected what I was seeing: I changed One Riverside, originally planned as a luxury rental tower, into condominiums. It became the first new ground-up Center City high-rise condominium started after the financial crisis.
We bet the buyer had returned. They had — and they surprised us. Buyers combined residences because they wanted more space, often 2,500 to 3,000 square feet. They weren’t downsizing in the conventional sense. They were rightsizing their lives, wanting less maintenance, not necessarily less living. The loft renter of the 1980s was back, with different expectations, greater wealth, and a lifetime of experience behind them. The product matured because the buyer matured.
We weren’t alone in reading the market that way. 500 Walnut launched sales at roughly the same time as One Riverside, giving Center City buyers two new ground-up towers to choose from at once. The Laurel came a bit later, opening sales toward the tail end of One Riverside’s sellout, which kept that first wave of post-recession construction rolling into the next phase of the cycle.
The shift was significant enough that national and international publications began documenting it in real time. In June 2017, The New York Times’ Square Feet column reported on developers luring buyers back to cities, opening with a suburban Philadelphia empty-nest couple trading a 3,500-square-foot house for a luxury Center City high-rise. In March 2018, the Financial Times reported on Philadelphia’s condo boom and the growing demand from baby boomers and younger urban buyers.
By 2017, Philadelphia recorded a then-record number of million-dollar-plus condominium transactions. The upper end of the market was no longer a handful of trophy sales. It had become a legitimate market segment. Sometimes the market does not simply recover — it comes back different. The 2015–2018 cycle was not only an economic recovery. It was a demographic cycle intersecting with a real estate cycle.
A Pandemic: The City Itself Gets Tested
Then came a different kind of shock. COVID-19 challenged the premise of city living. Restaurants closed. Theaters went dark. Offices emptied. Elevators felt uncomfortable. For a time, the suburban house that many empty nesters had been keen to leave suddenly looked pretty appealing.
At the same time, mortgage rates fell to historic lows, creating one of the strangest real estate environments I have ever seen: extraordinarily cheap money paired with extraordinary uncertainty about cities, and social distancing protocols that made construction challenging.
Transactions slowed, and the downtown lifestyle was interrupted. But the reasons people valued Center City didn’t disappear. By 2022, the median condominium price in Core Center City had moved above its 2019 pre-pandemic level, according to Center City District.
By the time Arthaus came to market, the competitive landscape had grown considerably. Arthaus and 2100 Hamilton were selling at the same time, and the Laurel — which had started earlier than either— was still selling too. That sustained, overlapping demand throughout so many buildings, spanning nearly a decade, signaled how far the market had matured.
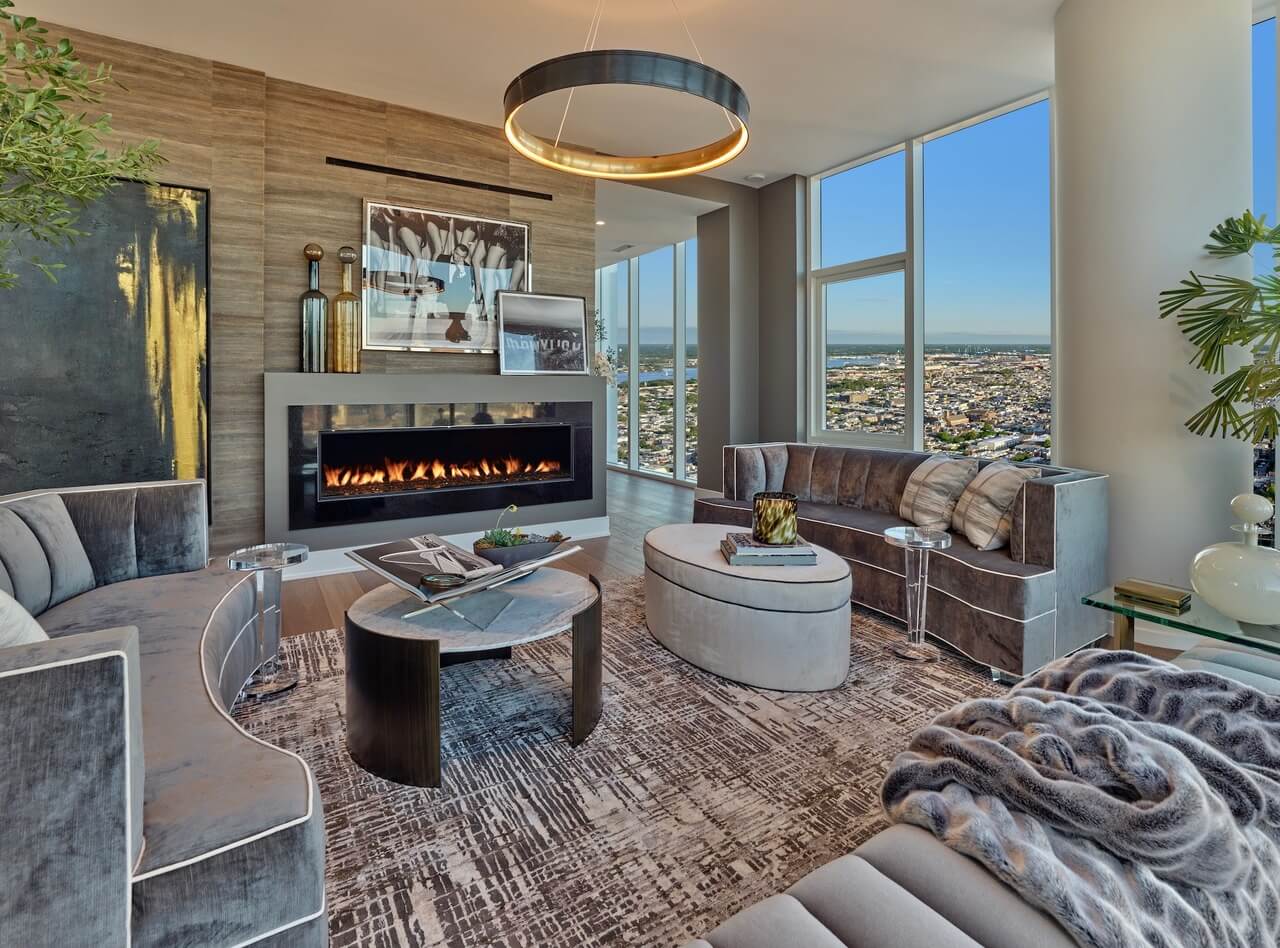
One thing the pandemic exposed almost overnight was how people actually wanted to live and work — and it’s here that I think Arthaus reveals its own instructive story. Years before anyone had heard of COVID-19, we designed dedicated home-office space as a standard feature, not an afterthought. We also emphasized wellness, outdoor gardens, extensive resident amenities, dog facilities, parking, and services that make a lock-and-leave urban life easier. None of that predicted a pandemic. It reflected trends we could already see in how luxury buyers wanted to live.
Anticipating how people would actually want to live wasn't a guess. It was part of the design brief —the buildings that are worth owning are the ones designed for how people will want to live years from now, not just today.
When the pandemic hit, those choices became more consequential. Residents who suddenly needed to work from home already had space to do it well, while the building’s wellness, outdoor, and service-oriented features aligned with needs that had quickly become more important. Design decisions made years earlier helped the building remain relevant when daily life changed almost overnight.
COVID reinforced another lesson: a real estate market can pause because of external events without permanently changing the desirability of the real estate itself. I’ve believed the key is having an inside track on luxury buyer sentiment, which we have consistently had for 40 years. Every single day we are talking with luxury buyers about how they are working and living. All this frontline data gathering helps us make informed decisions about future projects. In other words, we can make educated bets on how luxury buyers will want to live years from now. Those features are incorporated into floorplans and amenities of the next project. This is what separates real estate that holds up from real estate that merely holds on.
2022–2026: High Rates, Higher Costs and Less New Supply
The next cycle arrived quickly. Mortgage rates rose from pandemic-era lows to levels buyers had not seen in years. Construction financing became more expensive. Labor and material costs increased. Buyers became more deliberate, and transaction velocity slowed.
Again, it is easy to look at those conditions and assume they are permanent. They are not. But high interest rates have an effect that is often overlooked: they don’t simply make today’s purchases more expensive. They also make tomorrow’s buildings harder to finance and build.
Real estate development has a long cycle. When capital becomes expensive, projects are delayed or canceled. Land still must be assembled. Buildings still must be designed and approved. Financing still has to be secured. Construction still takes years. That means today’s difficult development environment can become tomorrow’s supply constraint.
For a long-term luxury buyer, the question is therefore not only, ‘Where is the market today?’ It is also, ‘What will exist to compete with this residence five or ten years from now — and what would it cost to reproduce it?’
Look at today’s pipeline, and that question largely answers itself. A new ground-up, for-sale, high-rise condominium breaking ground in 2028 — itself an optimistic timeline — couldn’t realistically open before 2032, once you account for design, approvals, financing, and construction. Yet right now, nothing of that kind is in the planning stages. Nothing in the high-rise condominium category is on the radar for sale in Philadelphia. That points to a period of genuine product scarcity in luxury high-rise condominiums over the next several years—precisely the kind of replacement-cost dynamic that supports the value of the buildings that already exist.
Why Philadelphia Has Behaved Differently Than Other Cities
Philadelphia’s luxury condominium market has historically been driven much more by people who actually intend to live here than by international investors or speculative second-home buyers. Its buyers come from Center City itself, the Main Line and surrounding suburbs, and from people with deep family, professional, medical, and cultural ties to the region.
That can make the market less liquid — there are fewer people capable of purchasing a $3 million or $5 million residence here than in Manhattan. But it may also add to resilience. People are not only buying an asset. They are buying proximity to children and grandchildren, world-class medicine and universities, restaurants, arts and culture, walkability, and a standard of urban life that remains considerably less expensive than in several peer cities. New York is close enough to reach easily. The Jersey Shore and the mountains are close enough to shape weekends. Philadelphia offers a remarkably complete lifestyle within a relatively compact geography.
That does not make the market immune to cycles. It gives the market a different foundation.
Protected Value. Peace of Mind.
Over the years, I’ve come to think about luxury real estate in two terms: protected value and peace of mind.
Protected value does not mean a property never declines in price, and no honest developer can promise that. Nor is a primary residence an investment in the same way as a stock portfolio or an income-producing property; ownership carries taxes, fees, transaction costs, and ongoing expenses. But the right luxury condominium can be both a home and a durable real-estate asset. The strongest candidates are fundamentally good enough, scarce enough, and difficult enough to reproduce that they have a strong chance of remaining desirable through transitional market conditions.
Location matters. Architecture matters. Construction quality matters. Views, floor plans, amenities, and the building’s financial well-being matter. So does the neighborhood around it. Increasingly, replacement cost matters too: if the land, approvals, financing, labor and materials required to create a comparable building have become dramatically more expensive — or if the building could not realistically be reproduced at all — that scarcity becomes part of the value proposition. Peace of mind is the buyer side of the same equation: confidence that what you bought was designed to outlast the cycle that came before it and the cycles that will come after it.
What Four Decades Have Taught Me
I’ve watched Philadelphia’s luxury residential market evolve from converted warehouses to amenity-rich high-rises. I’ve watched interest rates move from the high teens to below 3 percent and back above 7 percent. I’ve watched credit disappear, return, and tighten again. And I’ve watched the buyer evolve from a young urban pioneer into a sophisticated city resident with new expectations about space, service, wellness, and daily life.
I’ve also watched excellent real estate get caught in terrible markets. That may be the most important lesson of all: a bad market and a bad property are not necessarily the same thing. Markets can temporarily obscure value. They cannot manufacture the qualities that make a building worth owning.
Forty years of cycles have convinced me the question isn’t simply whether Philadelphia condominiums hold their value. Some will hold it better than others. The more important question is why.
Markets rise and fall. Interest rates change. Buyers come and go. But the qualities that make exceptional real estate desirable are remarkably durable: an irreplaceable location, enduring architecture, excellent construction, thoughtful floor plans, meaningful amenities, protected views, and a building designed with enough foresight to remain relevant to the next generation of buyers.
One more ingredient isn’t visible in the marble, glass, or skyline views: the developer’s philosophy. Protected value begins with the discipline to build something exceptional. It continues with the financial strength and patience to protect that value when markets become difficult. Ultimately, it gives an owner something equally important: peace of mind.
Because every new condominium eventually becomes a resale. The best buildings are designed for that buyer, too.
The Bottom Line
Philadelphia’s history does not prove that every luxury condominium is a good investment. It shows why some properties emerge from market cycles stronger than others.
The right condominium can be both a home and a durable store of real estate value when its enduring qualities — and the philosophy behind the building — give future buyers compelling reasons to choose it again.
Protected value begins at the design table, continues through disciplined stewardship and ultimately delivers what buyers value most: peace of mind.
FAQ
Are Philadelphia luxury condos a good investment?
Some can be both exceptional homes and durable stores of real estate value, but not all condominiums are equally positioned to perform. Forty years of market cycles suggest that enduring location, architecture, construction, floor plans, amenities, views, building finances, scarcity, and disciplined stewardship matter more than trying to time a single quarter or year.
How did the 2007-2008 financial crisis affect Philadelphia's luxury condo prices?
Financing tightened and some buildings, like the Murano, sold distressed inventory at auction well below original asking prices. That reset buyer expectations market-wide, but it did not reflect the long-term value of every property. Buildings that held the line on price and reinvested in the product, like 10 Rittenhouse Square, recovered and ultimately became the city’s first high-rise condominiums to cross $1,000 per square foot.
What does “protected value” mean in real estate?
Protected value is a development and stewardship philosophy. It begins with creating something fundamentally good enough, scarce enough, and difficult enough to reproduce that it remains desirable through variable market conditions. It continues with sound building finances, reinvestment in the property, and pricing discipline when the market becomes difficult.
Did the pandemic permanently reduce demand for Center City living?
No. Transactions slowed during COVID-19, but by 2022 the median condominium price in Core Center City had moved above its 2019 pre-pandemic level, according to Center City District. Buildings designed with features like dedicated home-office space — a standard at Arthaus since it was designed, years before the pandemic — were especially well positioned for the move to remote and hybrid work.
Why does new construction cost matter to someone buying an existing condo?
High interest rates and construction costs don’t just make today’s purchases more expensive — they also delay or cancel tomorrow’s projects. Because development has a multi-year cycle, today’s difficult building environment can become tomorrow’s supply constraint, which supports the value of comparable existing residences.
About the Author
Carl Dranoff
Developer of Arthaus & Founder/CEO, Dranoff Properties
Carl Dranoff is President and CEO of Dranoff Properties, a civic leader, entrepreneur, and urban visionary who has spent more than three decades delivering landmark residential projects across Philadelphia, from the adaptive reuse of historic buildings to ground-up skyscrapers. His portfolio includes Symphony House, named “#1 High Rise in the Nation” by Multifamily Executive and Developer Magazine, One Riverside, and Arthaus. He has been named Developer of the Year by the Pennsylvania Builders Association, Entrepreneur of the Year by Ernst & Young, and one of Philadelphia Magazine’s “100 Most Influential People in Philadelphia.” Carl earned his B.S. in Civil Engineering from Drexel University and his MBA from Harvard Business School, and holds an Honorary Doctorate in Engineering from Drexel.
Author disclosure: Carl Dranoff is the developer of Arthaus and founder and CEO of Dranoff Properties. This article reflects his professional perspective and experience across four decades of Philadelphia real estate cycles. Readers considering a purchase are encouraged to review current market data and consult a qualified real estate or financial professional before deciding.
Sources
- The New York Times, Square Feet, Jon Hurdle, June 6, 2017: “Developers Lure Buyers to Cities, Even as Prices Stall.”
- Financial Times, March 23, 2018: “Philadelphia's Condo Boom Lures Hipsters and Baby-Boomers.”
- The Philadelphia Inquirer, 2007–2018: Reporting on Symphony House, 10 Rittenhouse, Two Liberty Place, One Riverside, the Ritz-Carlton Residences, 500 Walnut, The Laurel, 2100 Hamilton, Center City condo pricing and the emergence of Philadelphia's ultra-luxury market.
- Center City District: Housing and residential market reports documenting Greater Center City's condo inventory, sales activity, and post-COVID recovery.
- Freddie Mac Primary Mortgage Market Survey / Federal Reserve historical series: Historical 30-year fixed mortgage-rate context across the major real estate cycles discussed.